Five Financial Decisions That Made My Downshift Possible
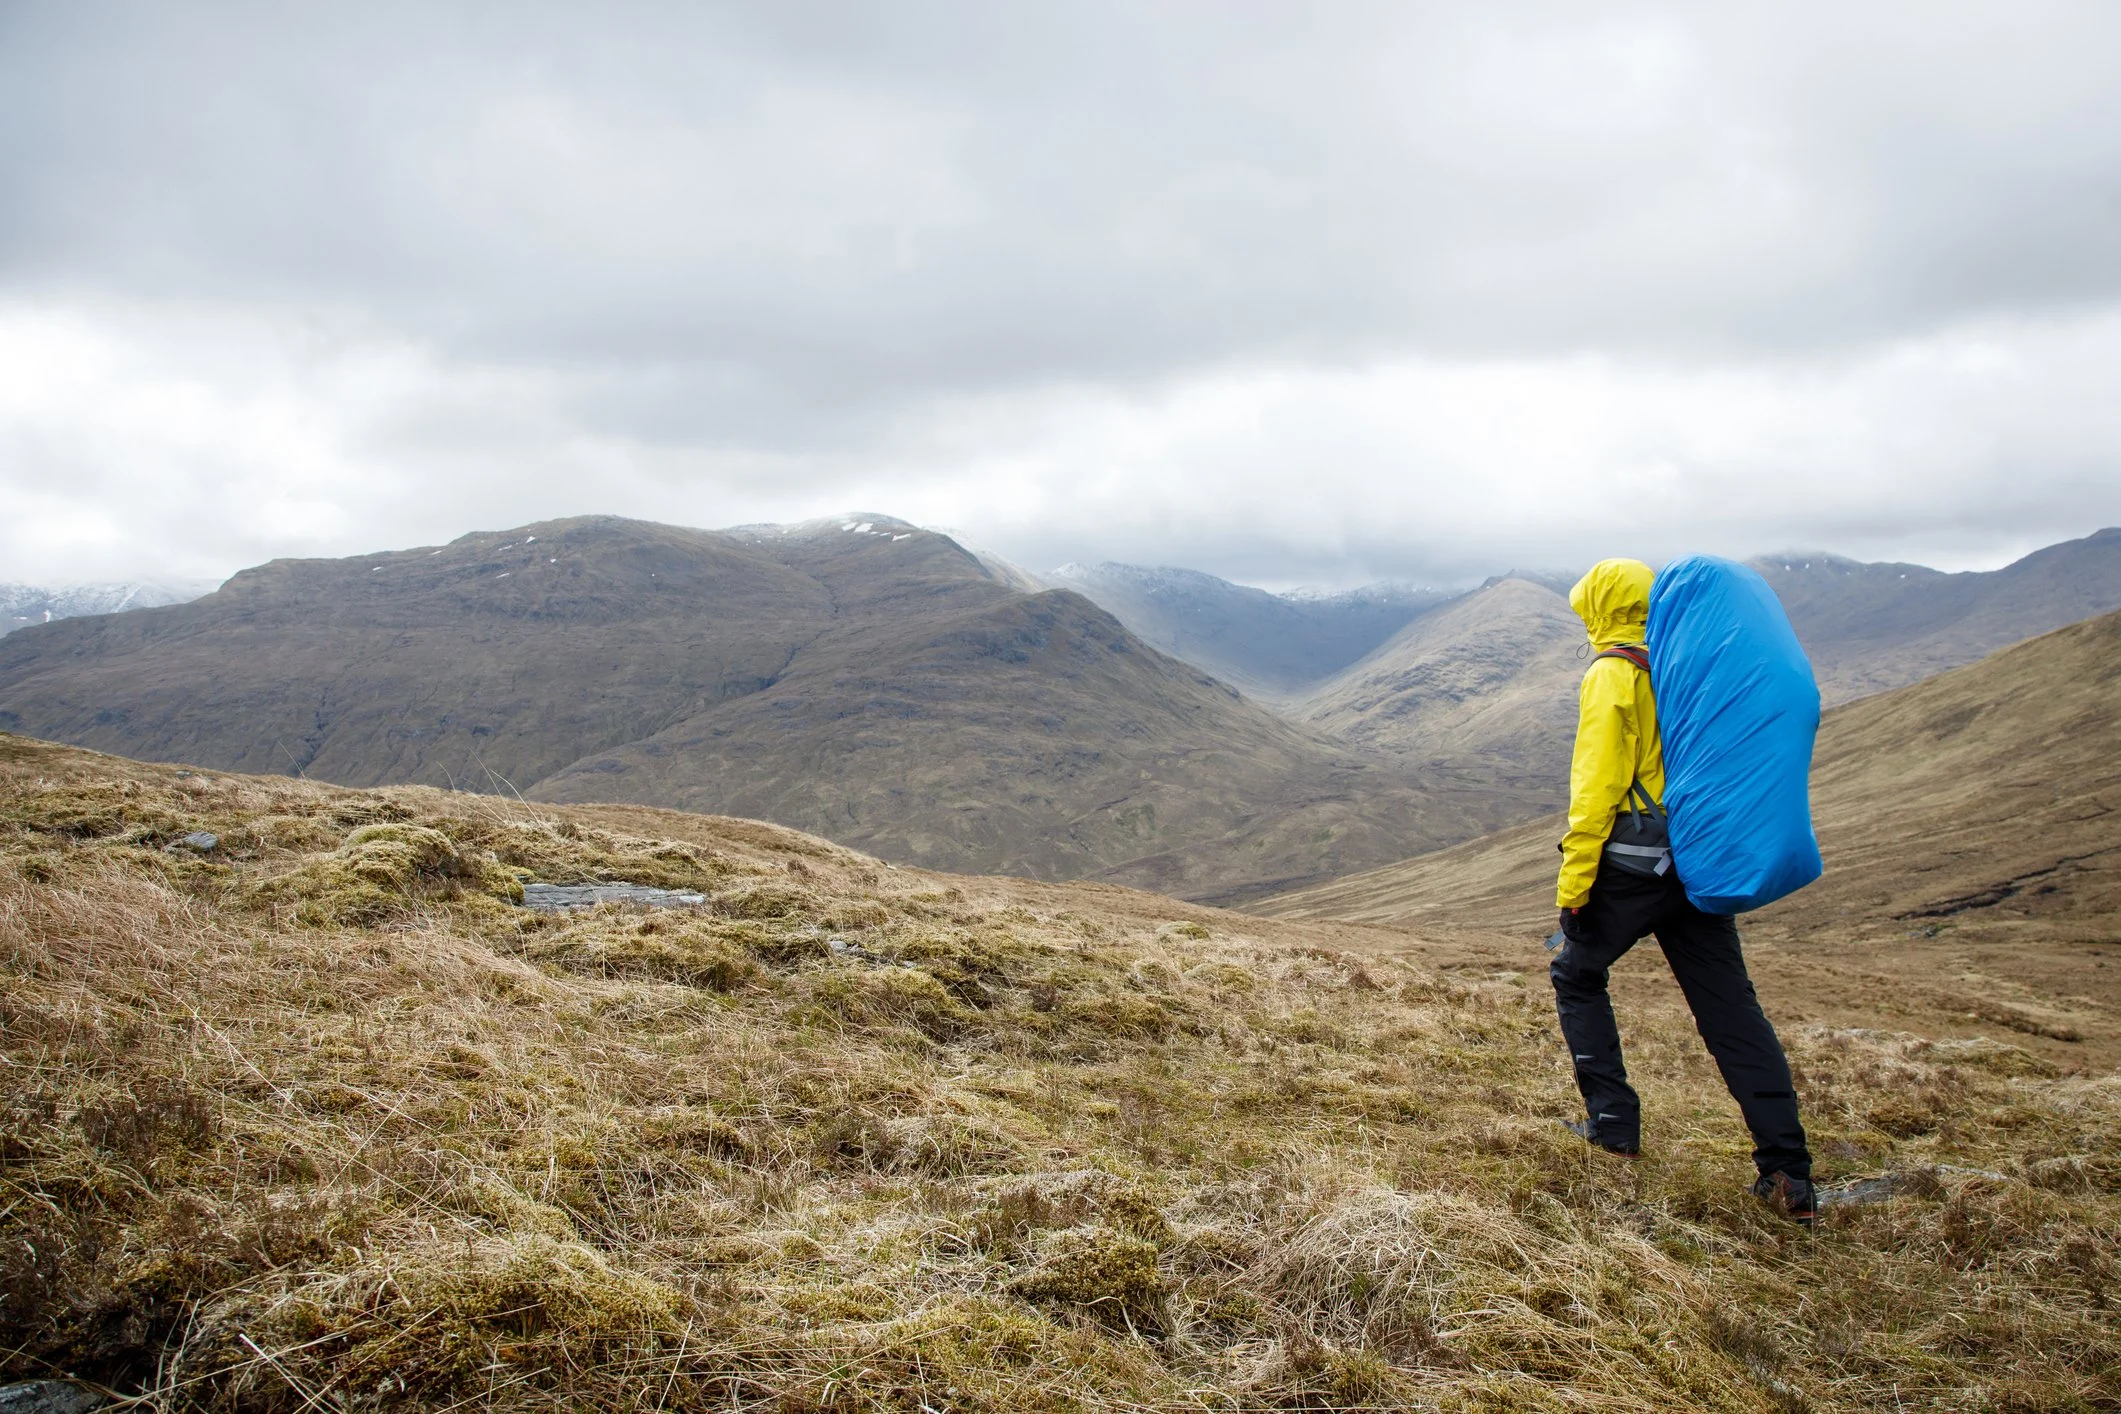
I was fourteen years old, brand new to Boy Scouts, and about to learn the most expensive lesson of my life for free.
Several friends from the football team and I had joined for the hiking and the wilderness skills. We were less enthusiastic about the uniforms. None of us had ever been backpacking, and when the first overnight trip came up, a weekend on the Appalachian Trail near Front Royal, Virginia, I packed the way a fourteen-year-old packs: with total confidence, zero knowledge, and no parental consultation.
I threw on some jeans, cotton socks, tennis shoes, and a long-sleeve t-shirt under a nylon football jacket. I borrowed my dad's olive green canvas frame pack from the 1960s. I strapped a cotton sleeping bag to the outside with a bungee cord, and it bounced against my back with every step. I brought a tarp to sleep on the ground, a lantern, a metal camp plate that rattled against everything in the pack so loudly you could hear me coming from a quarter mile away. Everything I brought was cotton or nylon. None of it belonged on a mountain in October.
And then it rained. I never thought to check. These were the days before weather apps or Google, but I never looked at the newspaper or watched the local weather report either.
What I didn't know, and what every experienced hiker learns the hard way or the easy way, is that wet cotton pulls heat from your body faster than bare skin. Hiking, I was uncomfortable but at least somewhat warm. Every time we stopped, the shivering started. Water against skin, soaked cotton everywhere, no way to get dry. After a long and wet day of hiking, we stopped to make camp. There was no campfire or making s'mores like I had imagined beforehand, and definitely no sleeping on a tarp under the stars like I had planned. There would have been a river running past me had I tried it. Thankfully a couple of older scouts from my high school let me sleep in their tent, and one of them had an extra blanket. That was good since my cotton sleeping bag was about 30 pounds and waterlogged. I was warmer but I still shivered through most of the night.
My dad had fought in Korea and Vietnam and spent twenty years in the Marines. His wool socks and his rain gear were in the basement in a box near the pack. I never thought to ask.
Sometimes life is a tough teacher, but I can tell you the next trip I went differently. I used money I had earned working part-time to buy an internal frame pack at REI with everything inside a few extra plastic trash bags. Wool socks, wool pants, polypropylene base layers. Waterproof hiking boots. A pack cover. A sleeping bag rated for the temperatures. A lightweight tent. Extra water and purification tablets. A headlamp instead of a lantern. Every ounce considered, every item earning its place. Four years later I was an Eagle Scout, wilderness tested, teaching dozens of younger kids the right way to backpack. The same lesson I was too headstrong to absorb at fourteen.
I've thought about that a lot as I've prepared for my downshift. The financial decisions I've learned to make over thirty years are the gear in my pack. Some of them I figured out early. Some of them I learned the hard way, the financial equivalent of wearing cotton in a rainstorm. And a few of them, like my dad's wool socks, were available to me long before I was smart enough to reach for them.
What I needed and didn't always have was someone a little further down the trail to help me pack wisely. Sometimes it was because I was too unwise or unwilling to ask, and sometimes it was because I didn't know I needed it. Now, approaching the end of my own trail, I want to be that person for you. Here are five decisions that kept me from freezing on the financial equivalent of an Appalachian mountainside.
Here are five that made the difference.
One: Dual Roth IRAs
This was the move that felt hardest relative to what we could see at the time.
For years my wife and I contributed to 401K plans up to the match. Adding to a Roth IRA meant using a chunk of our annual bonus to save for the future instead of enjoying the present. This was money we would rather be using for trips and experiences while our son was still at home. Saying no to a family trip so we could fund a retirement account we wouldn't touch for twenty-plus years required a kind of faith in the math that we didn't always feel, but we embraced it and ramped up the rate over time.
If your income limits direct contributions, a Backdoor Roth is worth understanding. I wrote about the mechanics and the pro rata rule in Part 2 of the Landing the Plane series. However you get the money in, it's worth the effort.
The dual Roth IRAs are now among our most valuable retirement assets. Not because of their total balance, but because of what they offer: tax-free withdrawals, no required minimum distributions, and two decades of compounding on contributions that felt painfully small in the early years.
It took us years to get there. The sequence was: capture the full 401K match, then fund part of each Roth, then max them both, then max the 401K, then max the HSA and resist using it for current-year medical expenses. Each step felt hard in combination and we didn't fund all of them simultaneously for a long time. The first few years of dual Roths felt like choosing between the life we wanted now and the life we were building for later.
We didn't stop living. We found creative ways to get the experiences we wanted for less, and we deferred the ones worth waiting for. I wrote about that trip after he graduated high school. It was worth every year we waited.
Two: The Brokerage Account I Didn't Understand Until Later
When we were in the younger family years, there were so many things competing for our income: sports, lessons, education, debt reduction, vehicles, and saving for the future. I didn't get it. We weren't even maxing out my 401K yet. But we did, and we put a pittance in there every month hoping it would grow into something. In retrospect, we were putting money in the wrong bucket before filling the right ones first, but we were saving, and the habit mattered more than the sequence.
But the biggest move that jumpstarted this part of our financial life didn't come from a plan. It came from a move that wasn't supposed to happen.
In the fall of 2017 we bought what we thought was our forever home. All brick, great neighborhood, strong school district. Four months later I was approached about a promotion that meant moving to Arizona. By the summer of 2018, we were gone.
We kept the house and rented it out. Our tenants were excellent for five years, paid on time, kept the home neat and tidy, and helped us pay down the mortgage as property values rose. When we sold it, we chose liquidity over reinvesting in another rental. That decision, putting the proceeds into our taxable brokerage account, gave us a running start. But the rental sale was a one-time event. What sustained the growth was a deliberate decision over the last several years to direct as much of our income as possible into taxable savings after maxing out every tax-advantaged account available to us.
The brokerage account is the bridge. Before 59.5, your 401K and IRAs are largely locked up without penalties. The brokerage is the war chest that buys your freedom in the gap years, and it's where sequence of returns risk protection lives: reserves you can draw from without selling equities in a down market.
The irony is that the season of my career that funded most of this account was also the hardest on my health and my family. The promotion that moved us to Arizona led to the Minnesota role, the peak earning years, the season of imbalance I've written about at length. From a financial perspective those years were tremendous. From a personal perspective they nearly broke me. I'm able to downshift in part because of the sacrifices of that season, and I'm choosing to downshift in part because of what that season cost. The same engine that built the freedom is the one I need to step away from. Both of those things are true at the same time.
The height of the peaks and valleys looks different for everyone. The principle underneath this move isn't the income level. It's the decision to prioritize liquidity outside of retirement accounts, at whatever scale you can manage, so you have options before 59.5.
Three: Paying Down and Then Off the House
This was both the hardest decision and the best one.
A few years ago, we were sitting on a 2.875% mortgage on a home we loved in a neighborhood we took real identity in. The math said keep it. At sub-3%, every dollar of extra payment could theoretically earn more in the market. That argument is true on a spreadsheet, and I'm not here to tell you to pay off a low-interest mortgage. In isolation, I'm not sure I would either, even in retirement. But for us the rate was answering the wrong question. The right question wasn't "should we pay this off?" It was "are we in the right house for the life we want to build?"
We weren't. The bigger home had become a lot to maintain: utilities, taxes, repairs, cleaning, pool maintenance, all of it. My wife wanted something simpler with lower overhead and the flexibility to lock it up for a long weekend and get to the mountains without worrying about it. She was right. The newer home is better laid out, has a pocket park next door that the dog claims as personal territory, lower utilities, lower taxes, and is walkable to restaurants and shopping we never had before. Better quality of life for less money.
We took on a 7.5% mortgage on a much smaller amount, and we were on a mission. Our bonus, merit increase, and tax refund went toward it, and within a year of downsizing we finished it.
What a paid-for home does to your monthly overhead in retirement is hard to overstate. Our base cost of living with no mortgage payment is low enough that our drawdown framework can sustain it through a lost decade without breaking. That isn't just a mathematical fact. It's a psychological one.
In retrospect it was the hardest move on this list psychologically and the one I'm most grateful for. Looking wealthy and building wealth are often in direct tension, and the decision to trade a bigger home for a paid-for one was the clearest example of choosing the second over the first. Knowing that when I downshift our base monthly burn rate is genuinely low is a huge psychological and mathematical boost. It's the gear that lets me sleep through a storm.
Four: Why I Never Paid 1%
This is the move I made by not making the move everyone expected.
I have several friends from college who are financial advisors or sell insurance. Great people. I respect what they do and I see real value for people who are uncomfortable making their own investment decisions. But I've never used an assets-under-management advisor, and with thirty years of perspective, I can see how much faster our portfolio grew without being weighted down by a 0.75% to 1% annual fee, even in down years.
I can remember my first full-time job at a nonprofit, reading the 403B plan options and choosing an S&P 500 index fund. I read a few books from the library, talked to my father-in-law, and clicked the box. That was the beginning. Over the decades the knowledge grew, and with it the conviction that paying 1% of my assets annually for someone to manage a portfolio I could manage myself with low-cost index funds was a trade I didn't want to make. Run the math on 1% AUM fees compounded over thirty years on a seven-figure portfolio and the number will make you physically uncomfortable.
The math gets worse in retirement. If you plan on withdrawing 4% of your investable assets, a full 25% of your target spending is going to an advisor. You may have noticed Bill Bengen's latest research suggests the safe withdrawal rate is closer to 4.7% or even 5% in some cases. For many people paying 1% AUM, the 4% rule was already the 5% rule. They just didn't realize 20% of their withdrawals were funding advice rather than their life.
What I do value, and what I'd recommend to anyone approaching a downshift, is project-based or hourly consulting with a fee-only advisor. Having a highly skilled professional build you a plan, run your numbers, and help you think through when and how to retire is worth every penny. I've done it twice: once several years ago when I first dreamt about the possibility of retiring early, and again recently to fact-check my own numbers against an independent model. I've written about both experiences and the peace they brought.
The distinction matters. An AUM advisor has a financial incentive to keep your money under management which conflicts with drawing down assets in retirement. A fee-only advisor has a financial incentive to give you good advice and send you on your way. For the cost of a few hours of professional time, you get the same quality of planning without the ongoing drag on your portfolio.
For those who want ongoing professional guidance without the AUM drag, a flat-fee fiduciary advisor is worth serious consideration. The time involved in managing an account doesn’t scale with balance. A flat annual fee gives you the same quality of advice whether your portfolio is $500K or $5M. Think of it like having a CPA help with your taxes as complexity grows: great advice at a reasonable and predictable price, and the value often exceeds the cost. As your assets grow, the cost advantage over AUM compounds in exactly the same way the fees would have compounded against you.
One more thought: if you're the money manager in your family, that flat-fee relationship also sets up your spouse for success if something happens to you. We haven't moved to that model yet, but it's on my radar. Part of loving your family well is making sure they aren't stranded if you're not around, particularly a spouse who isn't naturally drawn to spreadsheets, sequence of returns risk, and tax optimization deep dives.
Five: The Donor Advised Fund
This is the move that changed how we think about giving entirely, and it's the one I wish I'd understood ten years earlier.
We opened our DAF in 2023, so it's relatively recent in our financial journey. I'd heard about it for years but found the tax mechanics confusing, particularly the concept of resetting your cost basis. It took time to click. Around 2020 I started tax-loss harvesting during the market dip and began to understand the underlying concepts, but it was another three years before I applied them to giving.
Here's what makes it powerful, as simply as I can explain it.
Say you want to give $1,000 to a charity. You've been doing it by bank transfer or credit card. Instead, you donate $1,000 worth of appreciated shares from your brokerage account, shares you originally bought for $600. The charity receives the full $1,000. You get a $1,000 tax deduction. And the $400 in capital gains you would have owed if you'd sold those shares? Gone. Now take the $1,000 you would have given in cash, and use it to buy new shares of the same fund in your brokerage. Your cost basis resets to $1,000. You've given the same amount, received the same deduction, maintained the same investment balance, and eliminated a tax liability that would have grown with your portfolio. Unlike tax-loss harvesting, there are no wash sale rules. You can repurchase the exact same fund immediately with no repercussions.
Over time, as your portfolio grows, the math multiplies. I covered the tax strategy side of DAF contributions in Landing the Plane, Part 2 if you want the full picture of how it fits into a final working year.
There are layers beyond this that make the DAF even more useful. You can contribute in a higher-income year, take the full deduction now, and distribute to charities on your own schedule over the following years. If you have a year where income is unusually high, whether from a bonus, a property sale, or a one-time event, that is the year to front-load the DAF with appreciated shares. You get the strongest tax advantage when it matters most. If you don't typically itemize deductions, bunching two years of giving into one DAF contribution in alternating years can push you over the standard deduction threshold and make your generosity tax-efficient in a way that steady annual giving cannot. For us, it means we can keep supporting the organizations we love at a level we feel called to, regardless of what our income looks like in any given year.
One more benefit I didn't expect: anonymity. For organizations where we don't have a personal relationship, giving through the DAF means supporting their work without ending up on a mailing list by marking the donor confidential within the DAF. The charity just sees "ABC Brokerage Donor Advised Fund," no name, no contact info. I have an older family member who periodically gives $100 or $500 to mail solicitations. Because of the way some charities share mailing lists for active donors, she now receives multiple heart-wrenching appeal letters a day. We're helping her shift to anonymous gifts through a DAF to reduce this waste and pressure to give. It's a way to give generously while reducing the clutter and the marketing overhead for the charities themselves.
The DAF is the move on this list that connects money to meaning most directly. Every other move here is about building wealth. This one is about how to give wisely and efficiently to benefit others.
Finding What Was Already There
My dad's gear was in the basement the whole time. His wool socks, his rain gear, his decades of hard-won knowledge about what it takes to survive in rough conditions. He'd carried it across two wars. He would have told me everything I needed to know if I'd asked.
I didn't ask. I was fourteen and I thought I knew what I was doing. And I spent a miserable night shivering in a borrowed tent because I was too proud to reach for what was already there.
These five moves are the financial version of what was in that basement. Not all of them are complicated. Not all of them are obvious. But each one required me to stop, admit I didn't have the right gear, and go looking for better. Sometimes that meant reading a book. Sometimes it meant hiring a professional. Sometimes it meant listening to my wife when she said the house was too much and we needed something simpler and better. And sometimes it meant learning from other hikers who'd been further down the trail than I had, the financial conversations that changed how I thought about money, meaning, and what it actually costs to build a life worth living.
I'm packing for a different kind of trip now. Six months out from a downshift, and the gear feels ready. Not perfect, but ready. Not because I got everything right the first time, but because I've been on enough cold nights to know what belongs in the pack and what doesn't.
If you're on the trail, wherever you are, two questions before you go.
Which of these five moves are already in your pack, and which ones are you still putting off?
And who in your life has already walked the trail you're on, and have you asked them what they packed?
I'd love to hear some of your best lessons from your FI journey. Drop your thoughts in the comments below. I read every one and I answer every one. And if you want more stories from the trail and access to subscriber-only content, please join our Desert FI Insider list below.
Let's make wise choices and live a great life together.
🌵 Desert FI
Want to go deeper?
Become a Desert FI Insider. The gear was there. I just had to reach for it. That’s what this community is for. Insiders get Weekend Reflections every Sunday morning, free Insider-only resources like the FINE Number Calculator and the Well-Timed Exit Checklist, and access to live conversations like our recent subscriber-only Zoom call. If you’re not on the trail with us yet, join at DesertFI.org/join.
Already an Insider? Here are three posts worth exploring:
7 Questions to Ask in Building Your Downshift or Retirement Budget: on the seven questions behind a retirement budget
Not the Lattes. Here’s What Actually Retires You Early.: on the decisions that build your exit
Landing the Plane, Part 1: Building Your Drawdown Framework: on turning the numbers into a plan you can live on