7 Questions to Ask in Building Your Downshift or Retirement Budget
The white school bus climbed out of Belize City and into the mountains, air conditioning fighting the early summer heat as the jungle closed in on both sides. Jose, our guide, narrated the ninety-minute drive: the education system, the safety of the country, the life of a typical rural Belizean. My son was ten, sitting across from us and laughing every time Jose dropped one of his signature lines. "Un-Belize-able," he said at least three times during the drive. It stuck. A decade later we still say it.
As we gained elevation the air cooled and the humidity dropped. We arrived at Jaguar Paw, passed around bug spray, and followed Jose on a thirty-minute trek through the jungle. He stopped at different plants along the trail, explaining the local ecosystem and pointing out which ones were used as traditional medicines. The canopy filtered the light into green and gold. Everything smelled like wet earth and growing things.
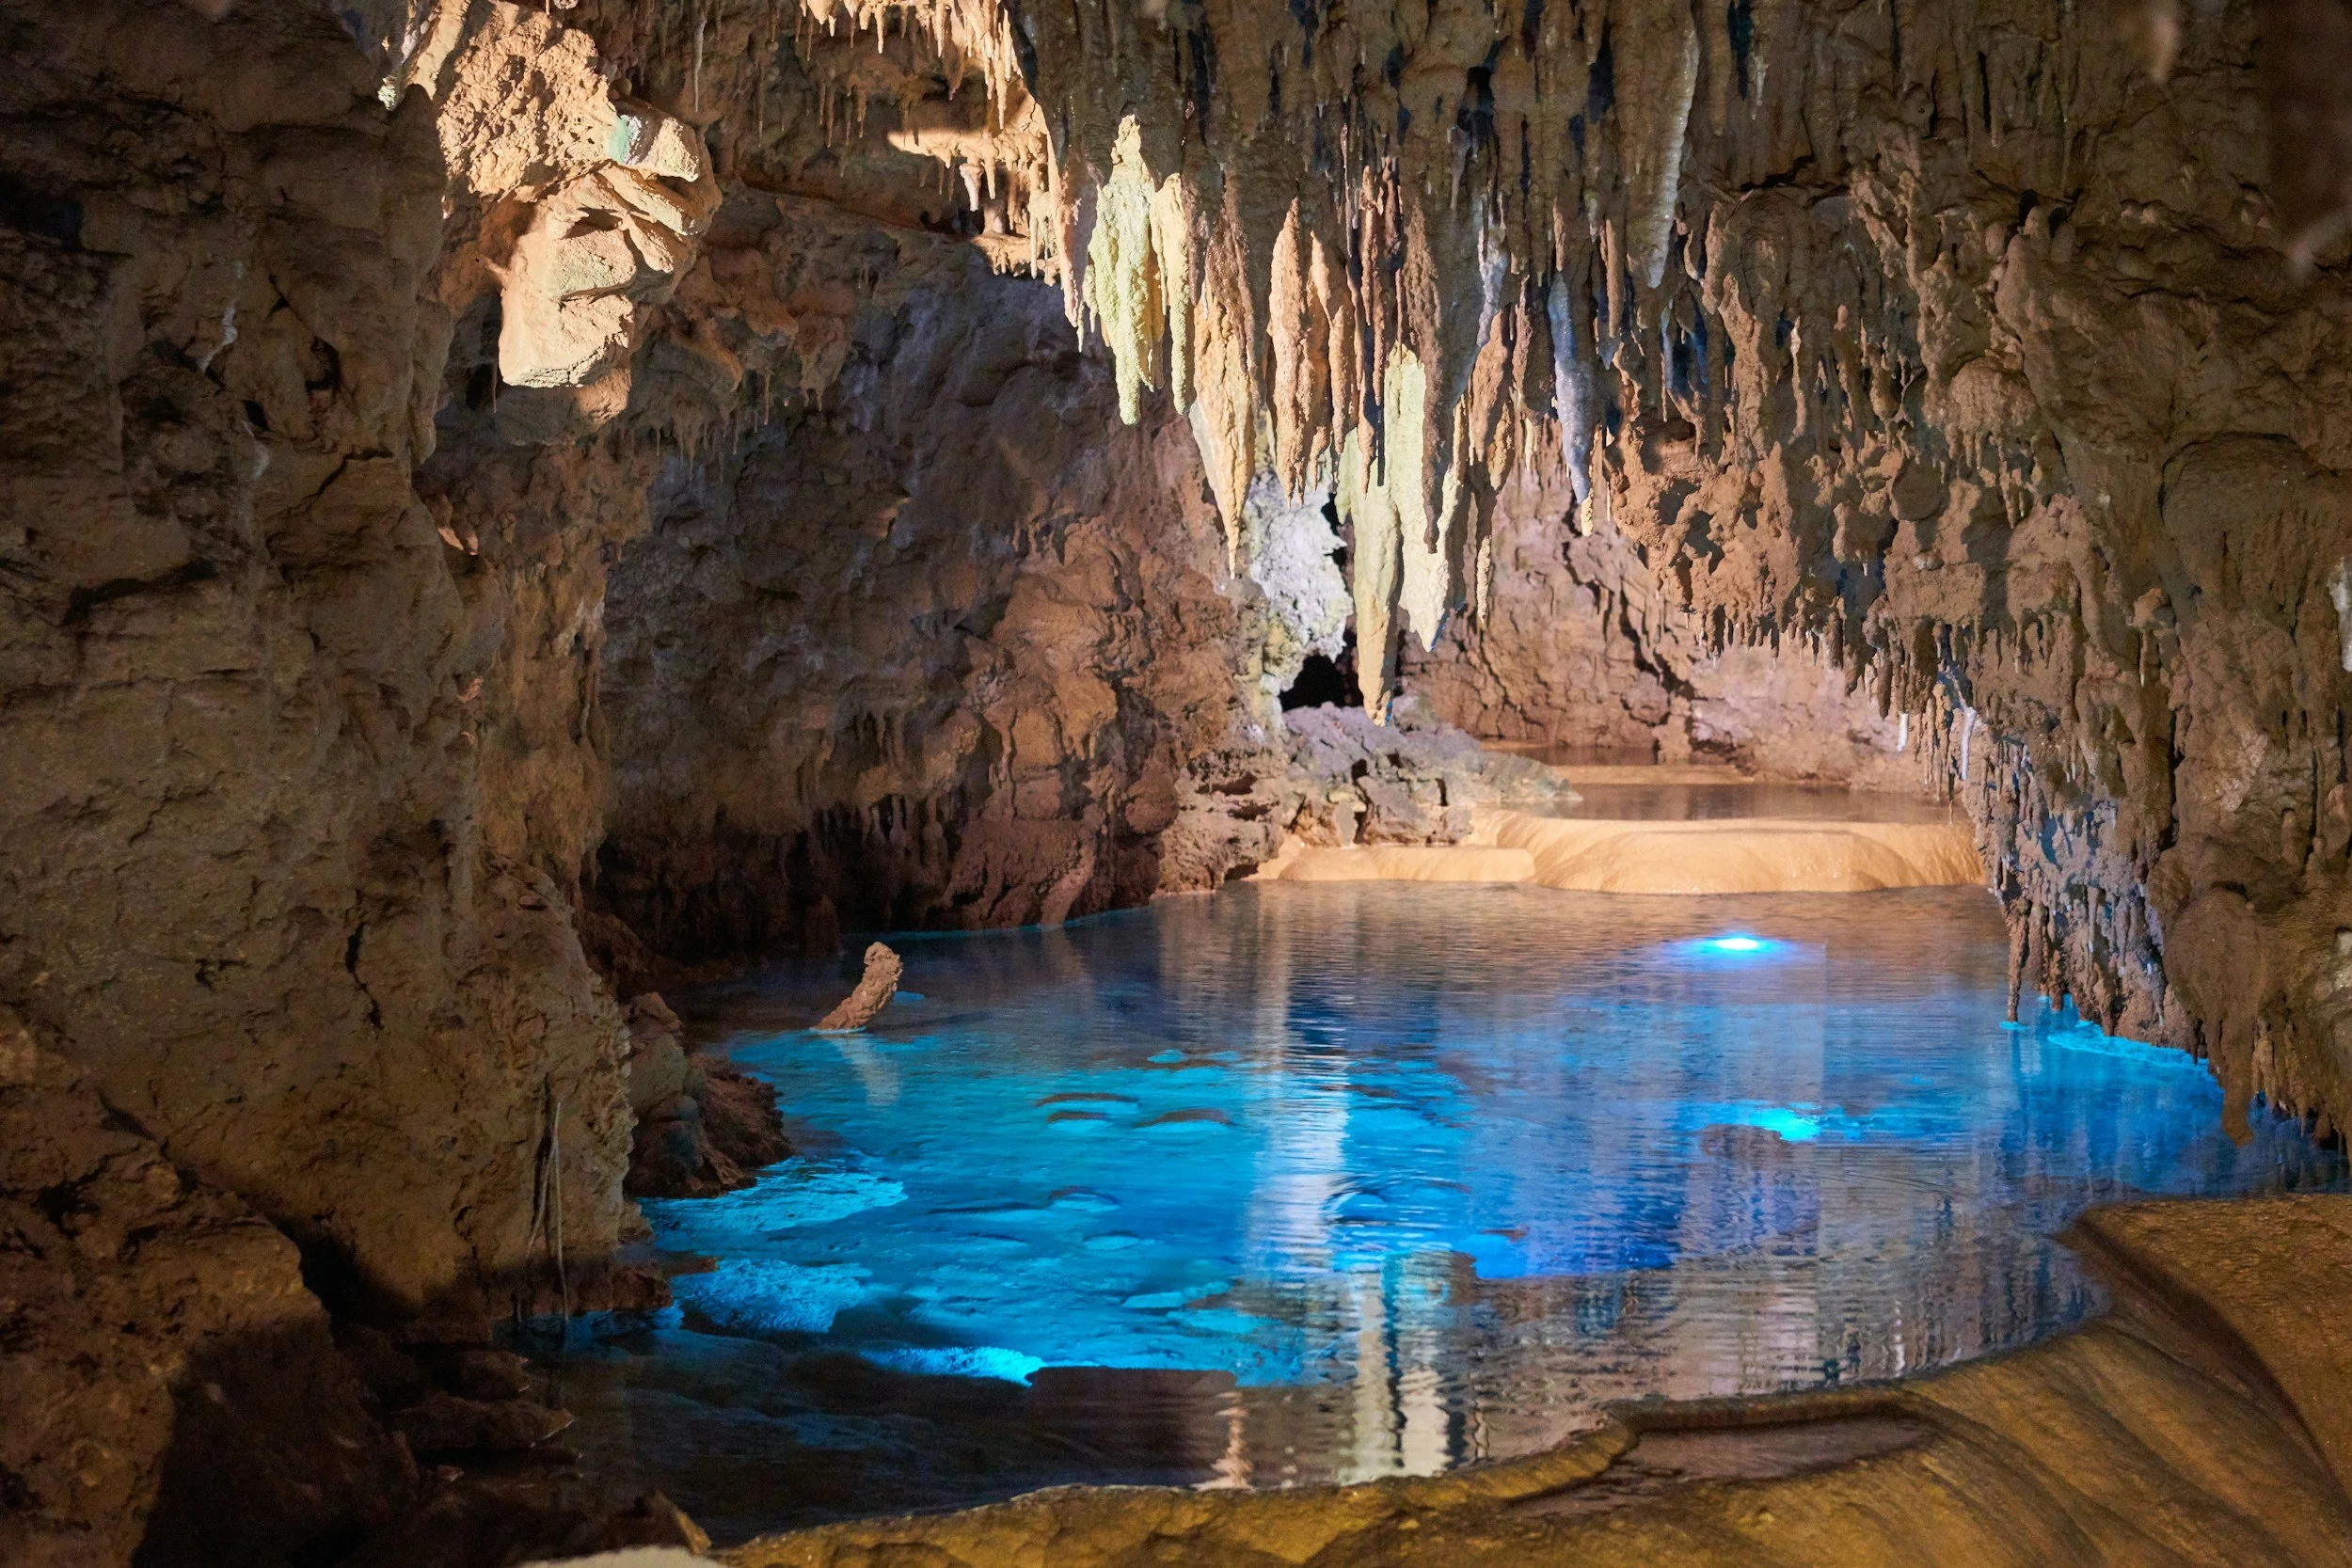
At the edge of the Cave Branch River we climbed onto inner tubes and pushed off into the current. The water was spring-fed, cool and clear against the warm morning. Limestone archways rose above us as we floated toward the cave mouth, and then we were inside, light giving way to darkness, the sound of the river amplified against the rock walls. Mist rose gently from the water and buffeted the stone above us. It felt like a lazy river going inside a Mayan cave.
Three guides managed the group. The lead rode at the front, another in the middle, a third at the rear. Each carried a stick, a headlamp, and wore lifeguard gear. They were relaxed but vigilant. A dozen vacationers floated between them, leaning back on their tubes, eyes adjusting to the darkness, trusting the current and the people who knew the cave.
I was enjoying the calm when I heard the lead guide say something to the middle guide in Spanish. "Keep your eyes open for culebras." Snakes.
I'd been a Spanish minor in college, twenty years earlier. Most of it had faded, but some words you don't forget. Nobody else in the group caught it. The guides didn't make a scene. They scanned the rocks and the water a little more carefully, adjusted course slightly, and the moment passed without anyone else knowing it had happened. I never saw a snake that day. But I appreciated that they were looking with vigilant eyes.
That is what a good guide does. They watch for the things you can't see, note the occasional thing worth watching for, and keep the journey moving without creating panic. The water is calm. The scenery is beautiful. And the guide's job is not to scare you off the river. It's to know where to look so you don't have to.
Afterwards we climbed out into the sunlight, laughed, took pictures, and loaded back onto the bus. Jose drove us to a pavilion in a small village for lunch: rice, beans, chicken, and fruit punch, smiles all around. We'd gone into the remote mountains of Belize, floated through a cave in the dark, and come out the other side with a story and a meal and the knowledge that the adventure had carried more beneath the surface than it felt like in the moment.
I've been thinking about that trip as I plan the financial side of my downshift. Retirement is the most beautiful trail I expect to walk, and it runs through unfamiliar country. A good map won't remove the risk. It helps you see the terrain clearly enough to move through it with confidence rather than fear. These are seven points on the map from someone who is studying it carefully before stepping into the water.
What Health Insurance Actually Costs When You Leave
It was a slow afternoon between Christmas and New Year's last year. I'd come in from a morning hike, the late December light angling through the blinds of my home office. The house was quiet. The inbox was quiet. I had two hours with nothing scheduled and a question I'd been putting off for months: what does health insurance actually cost when you're not on an employer plan?
I went to the ACA marketplace, put in our ages for the year we plan to leave, and started scrolling through dozens of plans with different deductibles, co-pays, and out-of-pocket maximums. The complexity was immediate. Within thirty minutes I was wading waist-deep in plan comparisons, subsidy calculations, and coverage trade-offs, and I could feel my eyes glazing over. We're in our early fifties, relatively healthy, no major ongoing medical needs beyond preventative care and the occasional injury from our hobbies. I knew post-exit insurance would be more expensive. I didn't know how much more.
I put $2,000 a month, $24,000 a year, into our downshift budget as a conservative estimate. It sat there for months, a large and theoretical number while I worked through the rest of the plan.
As my downshift gets closer, it has a lot more relevance. And the research has delivered some genuinely good news.
I recently listened to an excellent two-part episode of the Catching Up to FI podcast that covered strategies I hadn't considered: health sharing plans, short-term policies, farm bureau associations, and subsidy strategies. I also learned that COBRA can serve as a bridge for up to 18 months, and that you can elect it retroactively within 60 days of your separation date. Having been through a layoff during the Great Recession, my assumption had always been that COBRA was for people who were let go, not for people choosing to leave. I was wrong. In a stub year where you're only working part of the year, COBRA may be worth it for continuity of care with your existing doctors while you shop for ACA coverage in the fall for the following year.
The bigger surprise was closer to home. We had assumed our son would stay on our coverage after college. We set an expectation from an early age that our goal is to get him through college and working, and for him to go build his own great life. We have his back, but the clear expectation is that he gets a job and we taper him off the family health insurance, car insurance, and cell phone bills over time after he graduates.
When I priced plans for two adults versus a family of three, the difference was roughly $500 a month, or about $6,000 a year. A healthy young adult starting a career can often get his own coverage through an employer for very little, or an individual ACA plan for far less than it costs to add him to ours.
That one comparison moved our insurance budget from $24,000 to $18,000 per year and changed our approach entirely. The takeaway for me: be conservative in your early estimates, then refine aggressively as you get closer to launching. The number you fear is usually better than the number you find, but you have to do the work of finding it.
The question for you: Have you priced your post-exit health insurance against your actual projected income, or are you carrying a conservative estimate you haven't tested? And if you have adult children on your employer plan, have you compared the cost of keeping them on yours versus helping them get their own?
Where the Money Goes in Your Final Year
The final year of full-time work is the most complex financial year you'll ever navigate. Income may arrive from different sources on different schedules: regular pay, a bonus, a rental property sale, an ESOP distribution, stock compensation, or commission income. Each has a different tax treatment and a different optimal destination.
A few weeks ago I sat down with a legal pad and mapped potential income between now and my downshift, trying to trace where each dollar should land. The exercise took longer than I expected.
I've already pre-positioned five years of Treasury bonds, a six-month emergency fund, and a Life Fund. My first trial bond matures in mid-December this year, and I'll begin practicing my December 15 annual review. The structural framework is in place. What I'm working through now is the flow of income between now and departure.
My original thinking was to contribute to the 401K only up to the match. I've since changed my mind. I'm now strongly considering maxing it out, even if that means significantly reduced paychecks toward the end. Traditional 401K contributions provide tax savings in what is likely my last year of full-time work. Every future year's income should be lower, which means every future year's tax rate should be lower. Deductions are worth the most in the year your income is highest.
The HSA is another priority. I plan to max it out in my last year, partially through my employer's plan before departure and then finishing through my own HSA after I leave. We've treated the HSA as a stealth Roth for years: paying medical expenses out of pocket, saving receipts, and letting the balance grow tax-free. By saving additional dollars in the last year of work, we can lower our taxes and build another tax-free withdrawal source available before 59.5 if we need it.
The decision framework I'm building: complete all normal savings, including 401K, dual Roth IRAs, and HSA. Deploy one-time income to fund the non-working months after departure so we're not drawing from the portfolio in the stub year. In the final year, max the 401K before departure with catch-up contributions as a stretch goal, fund both Roths early in the year from a portion of the bonus, and direct any remaining overage into the taxable brokerage.
The question for you: Do you have a clear plan for where every dollar of final-year income goes, or are you making allocation decisions as each payment arrives? The difference between a framework and a series of reactions is meaningful, especially in the year where the tax implications are greatest.
Do You Actually Know Your Monthly Burn Rate?
I've been tracking our expenses in my own Excel budget for roughly twenty years. Over time it shifted from true budgeting with line-item accountability to more of a monitoring system as our savings rate grew. The more we learned to save, the less discretionary income there was for spending. We left ourselves flexibility but would course correct if things ran too high.
I have several years of actuals plus 2026 year-to-date, which gave us enough data to build a retirement budget we trust. We stripped out the categories that won't apply in retirement, savings, employer deductions, college expenses, and adjusted the ones that will change. Insurance will be higher. Professional clothing drops off. Young adult support expenses are tapering.
When my wife and I sat down to talk through it on a Saturday morning, it turned out to be one of those conversations that's easier than you expect when the data is already in front of you. We were directionally aligned on the big picture. The real discussion was around entertainment and travel going up, whether to keep the personal trainer or switch to a gym-only routine, and how the dog would shape our travel. Sedona and state parks, absolutely. A month in Europe, probably not until the next chapter of the next chapter. It honestly wasn't hard.
What I am benchmarking against is whether 2026 spending is tracking to that retirement plan. So far it is, with the exception of vacation spending running higher than typical due to family travel related to my mother's passing this year, her celebration of life at Lake Geneva and her interment at Arlington. Those are one-time expenses that won't recur, but they remind me that every retirement budget needs margin for the things you can't predict. The unplanned travel to honor my mother's memory is the most important spending we've done this year, and no spreadsheet in the world could have forecast it.
The question for you: If your paycheck stopped tomorrow, do you know within $500 what your household spends per month? Is that number from years of tracking, a recent estimate, or a guess? And have you and your spouse agreed on what that number should be in retirement, or is that conversation still ahead of you?
What Appears, What Disappears, and What Surprises You
Some line items vanish when you leave full-time work: disability insurance, the 401K deduction from your paycheck, the large tax withholding line on your W-2 paystub. Savings as a line item, which for years was one of our biggest monthly numbers, goes away entirely since you're no longer accumulating. Professional clothing drops off. College and young adult support expenses end.
Other line items appear for the first time or change shape. Estimated quarterly tax payments show up if you have earned income, Roth conversion income, or significant investment income. The Life Fund becomes a planned annual contribution rather than a bonus-driven decision. Out-of-pocket medical costs shift when your plan structure changes.
The first time I rebuilt our budget for retirement and deleted the savings line, I stared at the screen for ten seconds. That line had been the largest number on the spreadsheet for years, and removing it changed everything underneath it.
What surprised me was not the individual items but the net. I expected the disappearances to roughly offset the appearances. They don't, at least not cleanly. The line items that appear tend to be lumpy and less predictable than the ones that disappear, which makes the first year's cash flow harder to model with precision.
The one that caught me off guard: life insurance. We probably should have cancelled it earlier, but with our son in college and until we had solidified the downshift plan to the point where either of us could sustain the household alone, we kept it. Recently let it lapse. That was a line item we'd been paying for years past its usefulness, and I suspect many readers in our situation are doing the same.
The question for you: Can you make two lists right now, without opening a spreadsheet, of what disappears from your budget when you leave and what appears? After you make them from memory, check them against reality. The items you miss are the culebras.
If you’d like to go deeper into these seven questions, we’ve developed a free companion to this post, The Culebra Reflection Guide, with structured worksheets for each of these seven questions including the two-column exercise above. It’s free to Desert FI Insiders and yours when you join at DesertFI.org/join.
What Happens If Your Income Changes?
The standard retirement plan assumes income drops to zero and stays there. Mine doesn't, and if you've been reading about FINE, Financial Independence, Next Endeavor, yours may not either.
The FINE framework is built around the idea that financial independence doesn't have to mean full stop. A Next Endeavor, whether it's consulting, coaching, a small business, or meaningful part-time work done with full flexibility, can provide income that buffers investment returns, provides margin to retire years earlier than a full-stop model requires, and gives structure and purpose to the early retirement years.
The counterintuitive part is what you do with that income. Rather than spending it, you can wash out the earned income by directing it into a Solo 401K. It's like money coming in through the front door, staying in the tax-advantaged house, and then the income you actually live on comes out the back door in a more tax-efficient manner: long-term capital gains in a market-up year, a maturing bond in a market-down year, or a mixture of both in a flat year. You take deductions against earned income and live off of investments. It inverts the relationship many of us have with money during our working years.
This means your retirement plan needs to survive two scenarios: zero Next Endeavor income and moderate Next Endeavor income. The first is the conservative case that ensures you're safe regardless. The second is the case that provides margin, flexibility, and potentially decades of additional tax-advantaged growth. Build for the first. Hope for the second.
The question for you: Does your plan assume zero post-exit income, and if so, have you considered what even modest flexible income could do to your withdrawal rate, your tax bracket, and your long-term portfolio survival? If you're planning a Next Endeavor, have you mapped out how to shelter that income rather than simply spending it?
The Tax Window That Closes at 63
This may be the most valuable section in this post for readers who are five to ten years from their exit, and it's one that's not talked about enough.
The years between leaving full-time work and age 63 are the most tax-efficient window most early retirees will ever have. Your income is lower than it was while working. Your tax bracket is lower. And the opportunity to convert traditional retirement assets, 401K and traditional IRA balances, into Roth accounts at favorable rates is at its peak. Every dollar you convert grows tax-free from that point forward and comes out tax-free in retirement.
The impact is not small. On a morning Zoom call with "Jack," our fee-only CFP, he shared a year-by-year Roth conversion chart that mapped the strategy from my departure date through age 63. My wife and I were sitting side by side at the desk, and when the cumulative lifetime tax savings came into view, the number was staggering. Six figures over a lifetime when you account for decades of tax-free compounding and the elimination of required minimum distributions. That is not a rounding error. That's the kind of money that could fund a decade of health insurance premiums or help cover assisted living later in life. If much of your wealth is in traditional 401K, 403b, or IRA accounts, a disciplined conversion strategy could be your own long-term care insurance.
The balancing act is delicate. Every dollar of Roth conversion counts as income for the year, which affects your ACA subsidy eligibility. Convert too much in a single year and you lose the subsidy, potentially adding thousands to your health insurance costs. Convert too little and you leave tax-free growth on the table. The goal is to convert as much as possible each year while keeping your modified adjusted gross income below the subsidy threshold. That requires a level of precision that casual annual planning does not provide.
The window narrows at 63 because of Medicare. Medicare uses a two-year look-back to determine IRMAA, which is essentially a penalty tax on higher-income retirees. If your modified adjusted gross income exceeds certain thresholds, you pay significantly more for Medicare Parts B and D. A large Roth conversion at 63 shows up as income at 65 when Medicare pricing kicks in, triggering those surcharges and making the conversion less cost-effective. For someone who retired in their forties or early fifties, this could also be a natural inflection point to taper the Next Endeavor income. The FINE framework gives you flexibility to shift from part-time meaningful work toward full retirement as the conversion window closes and Medicare takes over your health coverage.
If you're planning to retire before 63, this window is a gift. If you're planning to retire at 63 or later, the window is much shorter and every year of delay shrinks it further. Either way, the key is having a year-by-year conversion plan, not a vague intention to "do some Roth conversions someday."
The question for you: Do you know when your tax optimization window opens and when it closes? Have you mapped out a Roth conversion strategy that balances lifetime tax savings against ACA subsidies and Medicare look-back thresholds? If you haven't, this may be the single highest-value conversation you can have with a fee-only advisor.
Building a Tracking System You'll Actually Use
I'm naturally the person who would update the spreadsheet every week. I'm trying something different in this season. I wrote in The Weekday World I Never Saw about experimenting with pieces of the life I'm building toward. This is one of them.
I'm trying to touch the budget only once a month. On the fifth of October I downloaded CSV files from our credit card companies and our bank and used AI to automate combining them, checking for duplicates, and translating different data formats into one consistent file. The time savings have been significant.
I've also shifted from static annual targets to trend-based tracking: measuring each category against its own 3-month and 6-month average rather than against a number I set in January and never update. The insight that drove the change was simple. Over the past decade, as our savings rate grew and our approach shifted gradually from strict budgeting to spending monitoring, the annual forecasts went stale. The variance column had stopped telling me anything useful because the targets it was comparing against no longer reflected how we actually spent.
The bigger shift is moving from tracking every dollar to focusing on the 20% of expense adjustments that drive 80% of the value. I list the top categories and top vendors each month and track sinking funds like the Life Fund and the travel budget separately. The system is designed to tell me whether we're on track without requiring me to wrestle with every transaction.
I know there are excellent online tools that do much of this automatically. I experimented with Monarch when I was helping my mother manage her finances in her last years. It reduced data entry and showed overall trends, but I personally felt less in control. Excel has been my native tool for thirty years, and something about having the data in a format I can manipulate directly gives me confidence that a dashboard view does not. That is a personal preference, not a recommendation. The right tool is the one you'll actually open on the fifth of every month.
The question for you: Be honest about your personality. Are you the person who will open the spreadsheet every month without fail, or the person who will do it faithfully for three months and then skip two? Whatever tracking system you choose, it should be designed for who you actually are, not who you aspire to be.
The View from the River
Floating through that cave on the Cave Branch River, I didn't know about the culebra until I heard the guide say the word. The water felt safe. The current was gentle. The scenery was beautiful. And underneath it all, someone was watching for things I couldn't see.
With my downshift in view, I'm finding that the retirement planning version of the same experience is remarkably similar. The plan feels ready. The reserves are in place. The framework is built. And every week I discover another question I hadn't thought to ask, another assumption worth testing, another line item worth pricing rather than estimating.
None of the culebras I've found have been fatal. The health insurance came in under budget. The son's coverage has a better solution than I assumed. The tax window is mapped. The tracking system is evolving. The things that surprised me were not the things I feared. They were the things I didn't know to look for, which is exactly why the research mattered.
After we climbed out of the cave and dried off in the Belizean sun, Jose drove us to a small village for lunch. The kind of meal where nobody checks the time and everybody leaves smiling. We'd gone into the mountains, floated through the dark, and come out the other side with a story worth telling.
The best guides I've had in life, including the One I follow into this next chapter and beyond, don't remove the risk. They watch for the things I can't see and provide wisdom to adjust the course when I need it.
I hope the first year of retirement feels something like that day on the river. An enjoyable journey with some risk beneath the surface, but with a good guide and a good plan, a great first year.
Two questions before you go:
What are the culebras that might be lurking in your own plan, and what would it look like to spot them before you launch?
What excites you most about the downshift you're planning, what worries you, and who can you talk through it with?
Drop your thoughts in the comments below. I read every one and I answer every one.
Let's make wise choices and live a great life together.
🌵 Desert FI
Want to go deeper?
Become a Desert FI Insider. Seven questions are easier to work through with company. Insiders get Weekend Reflections every Sunday morning plus free Insider-only resources, including the Culebra Reflection Guide, the companion to this post, with room to think and write. If you’re not on the trail with us yet, join at DesertFI.org/join.
Already an Insider? Here are three posts worth exploring:
Five Financial Decisions That Made My Downshift Possible: on the choices that built the margin
Landing the Plane, Part 1: Building Your Drawdown Framework: on turning the numbers into a plan you can live on
The Weekday World I Never Saw: on testing the life you’re planning before you leave