She Could Have Asked Me to Keep Working
What happened when we sat down with the biggest decision of our married life
I was about to fall in love. I didn't know it yet. It was the summer after my freshman year of college, and I'd become interested in the woman who would later become Mrs. Desert FI.
Our first date was technically not a date, since I'd made a point of saying so. I took her to the cliffs at Carderock along the Potomac, where a youth pastor named Steve had taught me to climb when I was sixteen. I've written about that day before, and about what it means to hold someone's life on a rope. She went over the edge with her knees shaking, trusting gear she didn't understand and a nineteen-year-old she barely knew.
What I left out of that story was what happened on the drive home.
We loaded the gear into my mom's black Chrysler LeBaron, which I'd borrowed for the occasion in place of my functional but considerably less impressive clunker. We drove the Beltway with the top down and the wind in our hair.
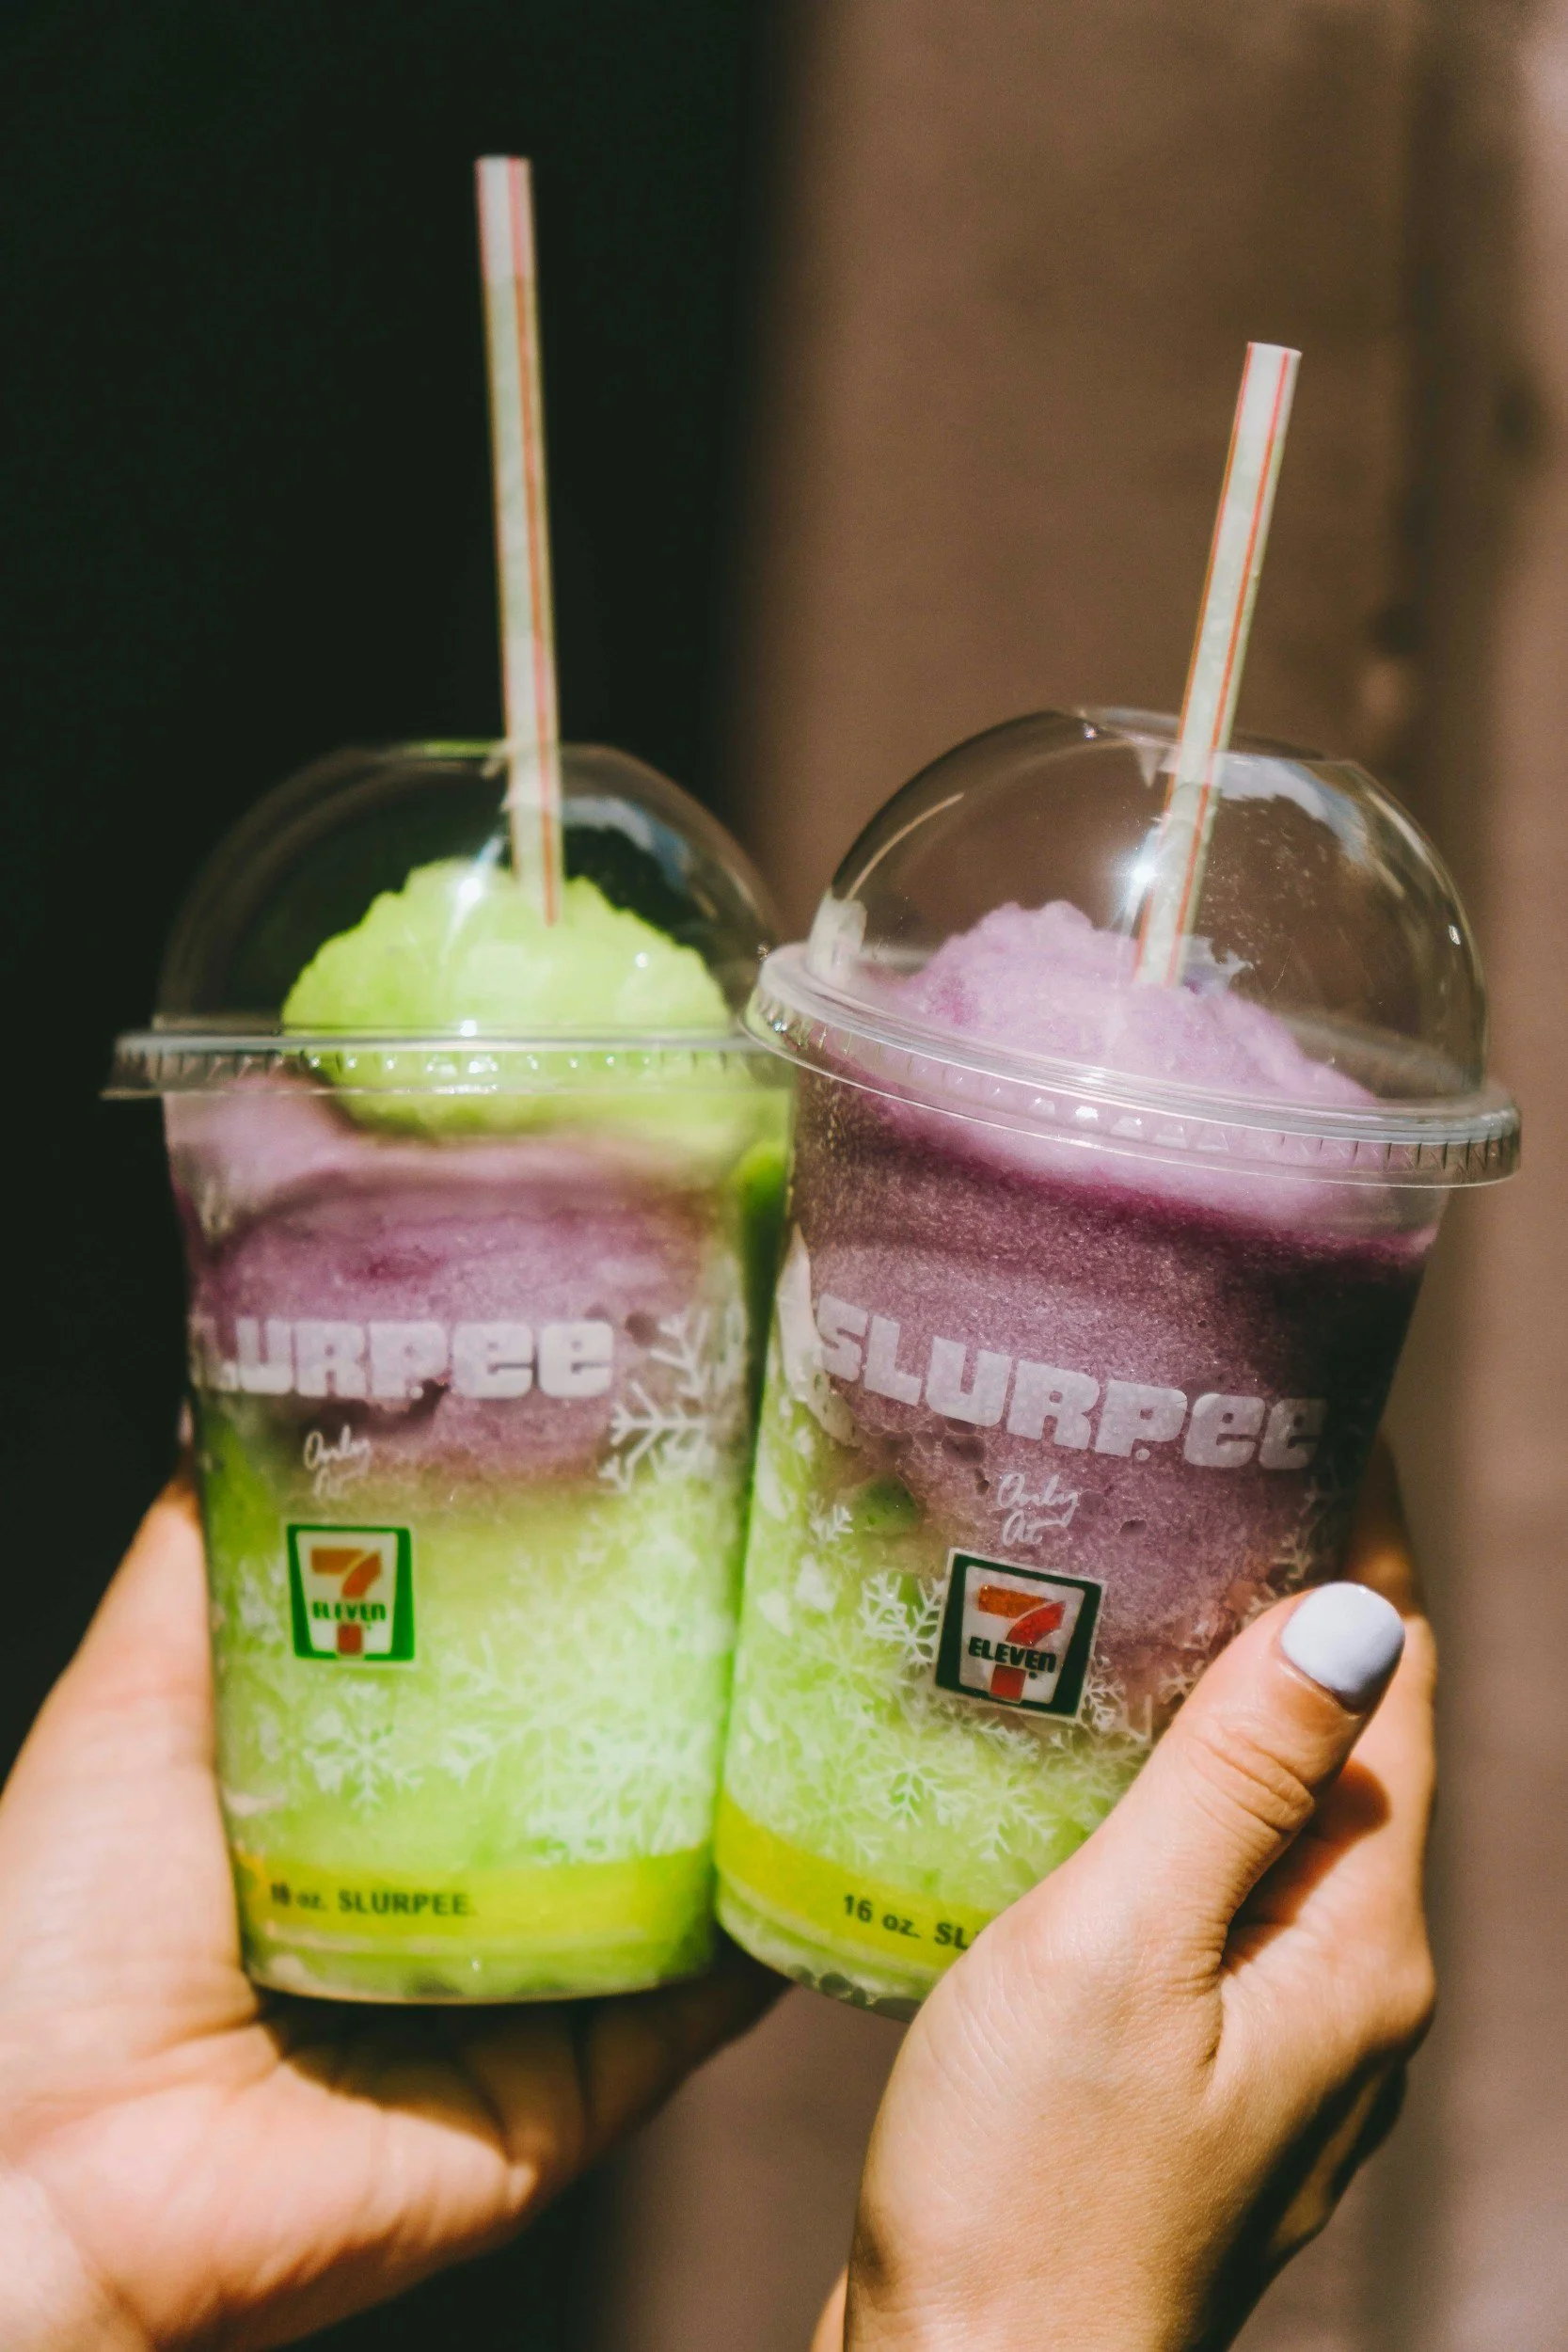
I was new in my faith then, still learning the difference between looking for signs and looking for wisdom. Somewhere along the way I'd prayed something strange, that my future wife would like fruit-flavored Slurpees. It wasn't a very spiritual thing to pray. But my dad was a quiet man, and one of the ways we bonded when I was a kid was the 7-Eleven stop on the drive home after a baseball or football game. He took cola. I took grape.
So I decided to put this new faith of mine to the test, and pulled in.
She sampled the orange. Then the cherry. Then she filled a whole cup with grape. I asked her about it, and she said words still burned into my mind to this day. I like any of them as long as they're fruit flavors.
I could hear the angelic choir. I may have fist pumped.
What I was after underneath the silliness was something I couldn't have articulated at nineteen. I wanted more than the love of my life. I wanted a best friend, someone I could sit with through a fiery sunset, fully relaxed and fully present, with something cold in hand and nothing that needed saying. These days it's usually a lot less sugar. The rest of it turned out to be exactly right.
I've matured since then. I don't believe there's necessarily a single right person out there waiting to be found. What I've learned is that marriage is built rather than discovered. It's made out of listening, taking a real interest in what someone else wants and needs, and choosing to love a person on the days you don't feel like it. That work is where the good part lives.
But at nineteen, in a 7-Eleven parking lot with a grape Slurpee, it felt like a sign.
Thirty Years Later, a Different Kind of Sign
This series started with the portfolio. Part 1 covered the drawdown framework, the bond ladder, the annual decision date. Part 2 covered the timing, the benefits, and the stub year. Somewhere in the middle of Part 2 I wrote a sentence and moved past it: retirement and downshift planning is a team sport.
That sentence deserved its own post.
Because I can model a bond ladder. I can run two thousand Monte Carlo simulations and stress-test a withdrawal rate against a lost decade. What I can't model is what happens to the other person in the house when my day stops having a shape.
I'm planning to downshift in early 2027, at fifty-three. That decision changes not only my life but my wife's. She left the workforce in 2005, but we've made every financial decision together for thirty years, and this one is no different. She gets a vote, and her input matters.
We've done this before. When our son was born we sold the house, moved to another state, and I started an MBA full-time, all inside a few weeks. That decision had the same shape as this one. You can talk it through as carefully as you want and you still don't find out whether you were right until years later. We decided it together, and it was uncomfortable, and we did it anyway.
I've written before about The Financial Conversations Most People Avoid, and about the five levels of disclosure that determine who you can actually talk to about money. This post is about the conversation at the top of that list. The one with the person you share an account with, a house with, and a future with.
What She Actually Said
The question we were wrestling through wasn't just whether I should retire. It was narrower and more useful than that. Are we comfortable with the plan? Do we believe we'll have enough? How will we respond if the market declines afterward? And most of all, is my wife on board with me downshifting at fifty-three?
Here's what she said, as close to word for word as I can render it.
Given our assets, she said, she honestly doesn't feel like it's her place to tell me to keep working until 60. You worked very hard so I could spend twenty-plus years at home with our son, which is what I always wanted, even after he left for college. You've worked a high-stress job. If you want to downshift, me telling you not to would be based on a feeling, and that's not right. I do think you should do something meaningful with your remaining years. As long as the money works and we don't have to majorly cut our lifestyle, I'm okay.
She said that a few days ago. I haven't stopped thinking about it since.
Why That Answer Is Harder Than It Sounds
That answer deserves a closer look, because I suspect some of you just read it and felt something protective on her behalf. She has a real concern and she set it aside. Isn't that exactly what a spouse shouldn't have to do?
Here's the fuller picture.
She isn't taking my word for it. Earlier this year we sat down with a CFP who had built an independent plan, and I'll come back to that meeting later, because it's the most useful thing we did. She mostly listened. She's less interested in the guardrail mechanics than I am, and she was there to take it in rather than to interrogate it.
She asked one important and thoughtful question. What happens with Social Security if I die early?
That was the right question, and it's the one I hadn't thought to ask. The answer, for our situation, is simpler than I expected. Nothing about the plan changes. She lives off the exact same plan until full retirement age, drawing from bonds, equities and cash the way the plan already lays out, and then receives the same payment she'd have received if I were still here.
One question. The one that mattered most to her, and the one with the most at stake.
So her position isn't blind trust. It's closer to this: I would feel more secure if you worked longer, but the plan is solid, and I trust you. And I don't want to tell you to work until you're 60 knowing you have other things you want to pursue.
That's a different thing than capitulating.
Her one condition is worth taking seriously, because "not majorly cutting our lifestyle" is a number rather than a feeling. I've written about the three versions of enough, and the one she's describing isn't the bare minimum. It's the one that sustains the life we spent thirty years building.
And here's the part I keep coming back to. It would have been so easy for her to do the opposite. A spouse who wants security has enormous power to feed one-more-year syndrome. Not through conflict. Through a moving goalpost. Let's get through this next bonus. Let's see how the market does. Let's wait until we hit the round number. Every individual request reasonable, the finish line receding forever, and nobody ever has to be the one who said no.
She didn't do that. She had a feeling, she named it out loud, and then she declined to spend my years on it.
That's different from deciding to stay on purpose, which I've written about and still believe in. The difference is whether there's a date at the end of it.
She did ask for something, and I want to be clear about that. She'd like me to stay through year-end and ideally through bonus season, to bank more before we start. That's a real ask with a real cost to me, and I agreed to it. What she declined to do was keep adding to the list.
If she had asked me to work until 55 or 60, I probably would have. She knew that. She said it anyway.
The Original "Working From Home"
I want to be careful about how her twenty years at home get described, because the shorthand does her a disservice.
Staying home was not the easier job. For most of those years it was the harder one, and I'm not sure it's close.
When our son was small it was constant. Coaching, correcting, feeding, dressing, supervising chores, tending to scraped knees, being the one available for every need the moment it arrived. As he got into school it changed shape without getting lighter. Meetings with teachers. Snacks for the class. Thirty to sixty minutes in the car line. Getting him on the bus. Being the one who knew which forms were due.
I did some of it. She carried the heavier load, and she carried it for two decades.
My job had hard weeks and stressful quarters and a Minnesota season I've written about at length. It also had a door I could close, an expense account, and colleagues who treated me like a professional. Hers had none of those things.
So when she says I worked hard so she could be home, I'd put it the other way around. We both worked. One of us got paid.
I should say plainly that none of this is about which spouse does which job. We have friends where the husband stayed home and the wife built the career, and it worked just as well. The arrangement we chose was ours, we decided it together, and we're glad we did. Every couple works that out for themselves, and the same goes for everything else in this post. The person who wants one more year of security isn't always the one at home, and it isn't always the wife.
She Solved This Before I Started Modeling It
Here's the part I didn't see coming, and it has reorganized how I think about this whole project.
While I've spent the last two years building spreadsheets toward a life with meaning and margin, my wife has been living one.
It started shifting when our son turned sixteen and began driving himself to school, first with her in the passenger seat, eventually on his own in a car he inherited when my father passed away. It deepened when he left for college. The daily work of raising him ended, and rather than drifting, she built something.
On a typical week now she works out two or three times. She spends several afternoons a week at a taco shop with bottomless iced tea, preparing the women's Bible study she leads at our church. She volunteers. She has lunch once or twice a week with a friend. She reads and studies for hours to keep growing and going deeper. In the evenings we walk the dog at sunset and run errands together, and every morning we catch up.
Friendships. Purpose. Structure. Physical health. Spiritual depth. Unhurried time.
That is the list. That's what I've been modeling my way toward, and she assembled it without a Monte Carlo simulation.
I think about a cooking class we took in Barcelona a few years ago. We'd been traveling with another couple, and the itinerary had been a mix of what all four of us wanted to see. Barcelona was the last stop, and by then it was just the two of us. I booked the class because I knew she'd love it. I'm good with breakfast food and very good on the grill. The complicated dishes, the ones that take real prep and technique, are hers, and she's exceptional at them. Watching me attempt to peel shrimp with a sharp knife was worth the price of admission to everyone in the room.
She didn't optimize that experience. She was just in it.
I've been running scenarios to buy my way back to a way of being she never lost.
What I'm Afraid Of
My list is shorter and less flattering.
First, I'm afraid I won't live the life I've been dreaming about. That I'll get thirty-plus hours a week of new freedom and squander the greatest gift I'll ever be handed. I've journaled about this. I have a clear vision of what a typical week should look like. It's going to take courage to actually live that week when there's no deadline forcing it.
Second, I want to keep some autonomy. To hike solo at a fast pace when I need to clear my head. To journal and study for a few hours somewhere with excellent coffee. To have lunch with friends often enough that it replaces the social contact my working years supplied whether I wanted it or not.
Third, I'm afraid that despite the spreadsheets, the tens of thousands of Monte Carlo simulations, and a plan a CFP signed off on, I missed something. Or that markets will behave differently than they have in the past. Mostly I'm afraid of going back to work in my field with my tail between my legs, because I couldn't cut spending, couldn't follow my own guardrails, or couldn't make early retirement work.
Most of those aren't rational fears. They're honest ones, and naming them is the only way I know to stay accountable to the life I say I want.
The Three Things She's Afraid Of
None of them are what I expected, and only one of them is about money.
Her routine. She said something to me recently that I've been carrying around since. I love you, but I don't want you to mess up my routine. I want to spend more time with you and I know we will, but I also really like my routine. We're going to have to work together to balance things.
What she's saying, and she's right, is: don't come in like a hurricane because you suddenly have time on your hands. Feel free to do more around the house. But I've been running this house for twenty years. Come in humbly and gently.
Her autonomy. She's an introvert. Right now I'm in my home office from early morning until evening, in meetings, heads down. The kitchen and living room where she spends her day are quiet. She reads. She plays a few games on her iPad. The house is hers, except for lunch and the occasional break when I wander out.
She's worried I'll want to talk all the time, or do everything together.
The money. She knows the plan is solid and she's still nervous, and she's clear-eyed about the fact that those are two different systems in her. She said it better than I could. It's more of an emotional feeling than a logical or mathematical one. It's not something to be solved. It'll just be an adjustment, and we won't know what it's like until we get there.
I am a planner. She is not. I want the itinerary set in September. She'd rather find out in May. After thirty years I've learned that her way is not a failure to plan. It's a different relationship with uncertainty, and it's frequently the healthier one.
The Best Thing That Came Out of Any of It
Her second fear is also mine.
Neither of us wants the pressure of being the other's entire social world. I love time with her and I want more of it. I also want a few hours a week that belong to nobody but me.
We were both a little afraid to say that, and we were afraid of the same thing. We want more time together, a schedule with meaning in it, room for our own hobbies and passions, and at least some of the rhythm each of us has built over thirty years.
That's not a compromise between two positions. That's the same answer, arrived at separately, and we nearly didn't find out because it felt impolite to say.
If your marriage is heading toward a transition like this, go looking for those overlapping fears and common ground. It's probably bigger than either of you thinks.
What We Actually Agreed To
I want to be specific here, because vague talk about being on the same page is how couples discover in year two that they were never on the same page at all.
We agreed that I'm clear to downshift in early 2027.
She'd like me to stay a few extra months to capture some additional savings, as I mentioned above.
We agreed the plan is sound. My own model and the independent one both hold.
And we agreed that if our net worth dropped significantly, one or both of us might go back to work, at least part-time. My written plan already accounts for that. There's a Next Endeavor income ramp, and a break-glass provision for returning to full-time work in a lower-stress role than the one I hold now if our real portfolio drops below a certain level. It's a low probability outcome based on the Monte Carlo results, but it's accounted for nonetheless.
That last agreement matters more than it looks. It means neither of us is pretending the plan is guaranteed.
Getting Her Into the Room
Early this year we hired a longtime friend who's a CFP to build an independent plan. I'll call him "Jack," as I have here before. She has no interest in income ramps, Roth conversion windows, or asset allocation specifics, and she'd tell you so herself, so I handled that part. I pulled the statements and screenshots, built out the scenarios for him to stress-test, and sent it all over so we could compare his output against our own model.
Then we sat down with him together for the results.
That mattered more than any spreadsheet I've ever built. Jack walked us both through four carefully constructed scenarios and the probability of success for each. In the worst case, we ran a sensitivity analysis and found that about $20,000 a year would move us above a 90% probability of success. Twenty thousand in reduced spending, twenty thousand in Next Endeavor income, or any combination of the two. Ten and ten. Fifteen and five.
That's the number we keep coming back to, because it holds up even when several things go wrong at once. Bad markets, a Next Endeavor that ramps more slowly than we expect, inflation running hotter than anyone planned for. Even in that stack of bad outcomes, twenty thousand a year is the needle mover. It could be consulting. It could be seasonal work. It could be driving for a rideshare company three days a week. The source matters less than the number.
She heard all of that from a professional, in a room, with a chance to ask her own questions. Not from her husband over dinner.
If you do one thing from this post, do that one. Bring your spouse into the room with a trusted advisor. The plan stops being your project and becomes something you both looked at.
One Thing I've Never Written About
I keep a letter. Five to seven pages, updated every year, in our safe deposit box. It opens with a personal note about what to do if I should die unexpectedly. After that it contains advice and a list of every account, where the documents live, how to get access, who to call, what she's entitled to, and what to do in the first thirty days.
I don't think of that as estate planning. I think of it as part of loving her well until the end. Much of it is already accessible to her, but I don't want her cobbling it together while facing something none of us ever want to face.
That's possible because of how we've handled money for thirty years. Every account joint, every title joint, full visibility for both of us, and an annual review that's a question rather than a briefing. Here's what we earned, saved, and spent. Anything surprise you? Anything you'd like to adjust?
That arrangement came out of premarital counseling, and it has worked for us because there's a trust level underneath it. I know that isn't everyone's story, and plenty of good marriages run on different systems. Use whatever structure fits yours. The letter works either way.
What the First Year Might Look Like
She wants to travel more. A big trip or two, some long weekends, a national park. I joke about leaving for New Zealand or Australia on short notice, and about watching for direct flight sales, and she responds warmly enough that I think she's in on an adventure like that eventually. Assuming we find good care for the dog.
What she said, and I love this, is that she'd like the trips to be more relaxing.
Our Europe trips have always been compressed. We packed them, because the flights cost what they cost and the vacation days were finite, so we saw everything. She'd rather take one city slowly. Get to know it. Leave room for something spontaneous.
That's a different kind of travel, and it's only available on the other side of this.
She isn't planning it yet. She wants to feel it out when we get there. I'm learning not to hand her an itinerary.
What I'd Tell Another Couple
Ask the emotional question, not the math question. I already knew the plan worked. What I didn't know was what she was afraid of, and none of the three things were what I would have guessed.
Get them in the room with someone who isn't you. A third party running scenarios in front of both of you changes the conversation permanently. It stops being your plan.
If the conversation keeps stalling, get help with it. A CFP can settle the financial questions, and a counselor can help with the ones underneath. There's no prize for working this out alone, and a decision this size deserves more than two people talking past each other at the kitchen table.
Ask what they don't want. Not just what they're looking forward to. "Don't improve my routines" was worth more to me than any list of hopes.
Go looking for the overlap in your fears. Ours turned out to be the same fear. We almost never found that out.
Say the fear out loud, even if you're not going to act on it. She named her hesitation as a feeling and then declined to let it drive the decision. I'd rather know than be protected from knowing.
Notice whether they've already figured out something you're still working on. Mine had.
Write the letter. If you died this week, could your spouse find everything? Five pages is a weekend's work. The future isn't guaranteed. Consider making a final gift of love to your spouse, just in case it comes sooner than you expect.
And if you're doing this alone, find one person to be honest with. A sibling, a friend, an advisor, someone who'll ask what you're afraid of and won't let you answer with a spreadsheet. The questions above still apply. You just have to go looking for the other side of them.
The Sign
At nineteen I decided a woman might be right for me because she pulled grape at a 7-Eleven.
At fifty-two I brought her the biggest decision of my adult life, and she said that asking me to wait on a feeling wouldn't be right.
Thirty years apart, and she's the one with the better relationship to signs.
I don't know what the first year is going to feel like. She's right that it's not a thing to be solved. We'll find a rhythm, or we'll find several, and some weeks will be awkward while we sort out who gets the kitchen and how much togetherness is the right amount. That's the part no spreadsheet covers.
What I do know is that the hardest part of this transition was never the withdrawal rate.
It was asking the person who's been living a great life for years whether there's room in it for me.
She said yes. Humbly and gently, please.
Two questions before you go:
If you're planning an exit, does your spouse or partner know what you're actually afraid of, and do you know what they're afraid of?
And if you've already had the conversation, what did they say that you didn't expect?
Tell me what you think in the comments below. A question you're stuck on, something here you think I got wrong, or how this went in your own house. I read every one and I answer every one.
Let's make wise choices and live a great life together.
🌵 Desert FI
If this resonated, Weekend Reflections goes out every Sunday morning: a personal letter on money, meaning, and the courage to build a life that finally feels like your own, plus every new post delivered so you never miss one. Join us at DesertFI.org/join.
Want to go deeper?
Become a Desert FI Insider. The conversations that matter most are easier with company. Insiders get Weekend Reflections every Sunday morning plus free Insider-only resources like a reflection guide with room to think and write. If you’re not on the trail with us yet, join at DesertFI.org/join.
Already an Insider? Here are three posts worth exploring:
The Retirement Line Item Nobody Budgets For: Adult Kids: three conversations to have before you leave full-time work
The Financial Conversations Most People Avoid: on finding people to talk honestly about money with
The Weekday World I Never Saw: on testing the life you’re planning before you leave